Last Updated on September 25, 2026 by teamobn
A workplace injury can create far more than an immediate medical problem. It may mean time away from work, reduced income, rehabilitation, ongoing medical appointments, uncertainty about whether the employee can return to the same job and, in serious cases, permanent limitations.
The scale of workplace injuries remains substantial. According to the U.S. Bureau of Labor Statistics, private industry employers reported approximately 2.5 million nonfatal workplace injuries and illnesses in 2024. The total recordable case rate was 2.3 cases per 100 full-time equivalent workers.
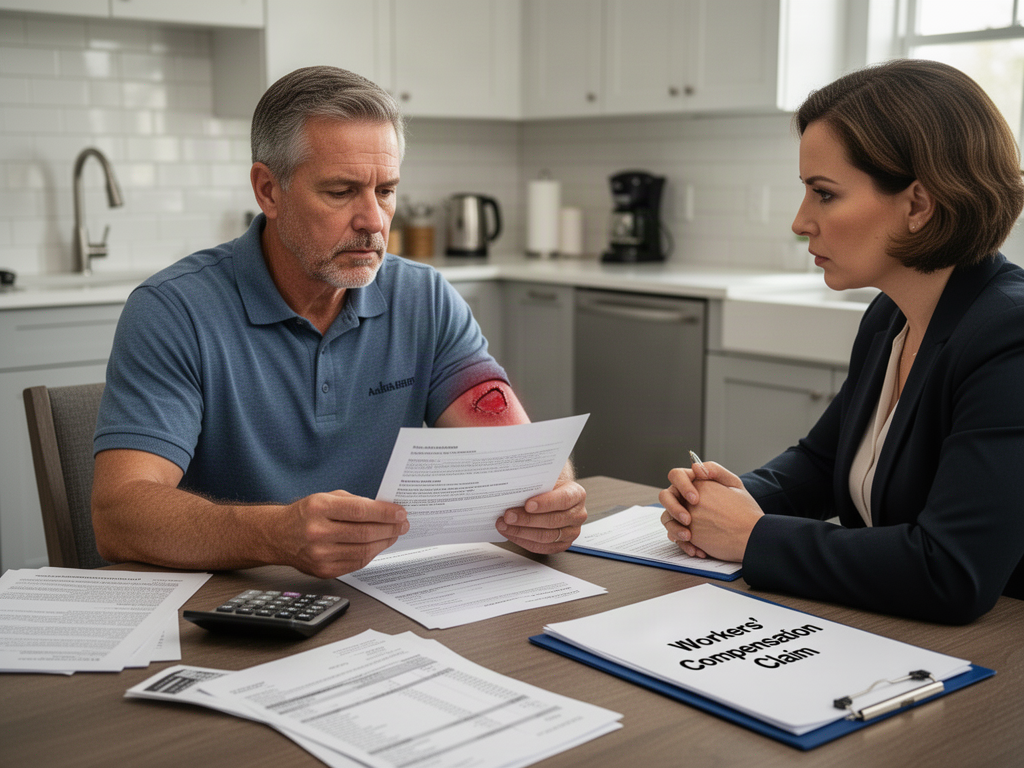
Workers’ compensation is designed to help address some of the financial consequences of a job-related injury or occupational illness. Depending on the state and the circumstances of the claim, benefits can include medical treatment, wage replacement, disability payments and vocational rehabilitation.
But receiving workers’ compensation benefits is not necessarily the same thing as settling a claim.
A worker might receive weekly benefits and medical treatment for months or even years without ever entering into a final settlement. In another case, the insurer and worker may negotiate a lump-sum agreement that brings some or all of the workers’ compensation claim to an end.
So, when does workers’ compensation offer a settlement?
There is no universal date. Settlement discussions may begin relatively early in some claims and much later in others. The timing is usually influenced by the worker’s medical condition, the likelihood of future treatment, whether permanent impairment remains, whether the employee can return to work, and whether the parties disagree about liability or benefits.
Understanding those factors helps explain why two apparently similar workplace injuries can follow very different settlement timelines.
Workers’ Compensation Rules Differ From State to State
The first point to understand is that workers’ compensation is not one national system for most employees.
Private-sector and state or local government workers generally fall under the workers’ compensation laws of the state in which they work or were injured. The U.S. Department of Labor administers programs covering certain federal employees and specialized groups, but it does not administer state workers’ compensation programs.
That means settlement terminology, procedures, benefit calculations and approval requirements can vary substantially between states.
For example, North Carolina recognizes a final settlement commonly known as a “clincher.” The North Carolina Industrial Commission describes a Compromise Settlement Agreement as a voluntary, complete and final settlement under which a negotiated amount is paid for disability and medical compensation claimed by the employee. The Commission must approve agreements to pay compensation.
Kentucky uses its own settlement process. Settlement agreements are generally submitted using Form 110 and must be reviewed and approved before taking effect.
For that reason, broad advice about workers’ compensation settlements should always be treated as a general guide rather than a substitute for the rules of the particular state involved.
Maximum Medical Improvement Is Often an Important Milestone
One of the most important stages in many workers’ compensation cases is maximum medical improvement, usually shortened to MMI.
MMI generally means the treating physician believes the worker’s medical condition has stabilized and that substantial additional improvement is not expected from further treatment. It does not necessarily mean that the worker has completely recovered.
Someone might reach MMI while still experiencing pain, restricted movement or reduced ability to perform certain kinds of work.
From a settlement perspective, MMI matters because uncertainty makes a claim difficult to value.
Consider an employee who has recently undergone back surgery. Three months after surgery, nobody may yet know whether that person will return to unrestricted work, require additional surgery, need long-term medication or be left with permanent lifting restrictions.
Trying to place a final value on the case at that stage involves considerable guesswork.
Once the worker’s condition stabilizes, there is usually more information available about:
- future medical treatment;
- permanent physical restrictions;
- the ability to return to the former job;
- possible reduced earning capacity;
- permanent impairment; and
- the likelihood of additional disability benefits.
For those reasons, insurers and injured workers often have more meaningful settlement discussions once the medical prognosis becomes clearer.
However, reaching MMI is not a universal legal requirement before settlement. Claims can sometimes settle earlier depending on state law and the circumstances. The trade-off is that settling before the long-term medical picture is understood can make it easier to underestimate future costs.
Permanent Impairment Can Affect the Value of the Claim
When an injury leaves a lasting physical limitation, a doctor may assign a permanent impairment rating.
An impairment rating attempts to quantify the percentage of permanent loss of function attributable to the injury. State law then determines how that rating affects workers’ compensation benefits.
The rating can therefore have significant financial consequences.
North Carolina, for example, allows a Form 26A agreement after the end of the healing period for payment of permanent partial disability benefits based on a physician’s evaluation of remaining permanent impairment. The North Carolina Industrial Commission also states that an employee is entitled to a second opinion specifically concerning the impairment percentage under certain circumstances.
An impairment rating should not automatically be confused with the value of an entire workers’ compensation claim. A settlement can involve considerably more than a percentage assigned to a particular body part.
Other factors can include future treatment, wage loss, work restrictions and whether the worker can realistically resume the same occupation.
Returning to Work Can Change Settlement Negotiations
Whether the employee returns to work is another major factor.
Suppose two workers suffer similar shoulder injuries.
The first worker completes rehabilitation and returns to the same position at the same salary with no significant restrictions.
The second worker reaches MMI but is permanently restricted from lifting more than 15 pounds and can no longer perform the physical job held before the injury.
The medical diagnoses might be similar, but the economic consequences are clearly different.
If an injury affects the employee’s ability to earn the same income, the potential value and structure of workers’ compensation benefits may change. Vocational rehabilitation or retraining may also become relevant depending on state law.
A successful return to work can therefore make the long-term financial exposure easier to calculate. Continued uncertainty about future employment can make settlement negotiations more complicated.
What Does a Workers’ Compensation Settlement Actually Cover?
This is where injured workers need to pay particularly close attention.
A settlement check is not necessarily “extra money” on top of future benefits. Depending on its terms, the payment may be intended to replace benefits that otherwise could have been paid over many years.
A settlement might address:
- past or future wage-loss benefits;
- permanent partial disability;
- future medical expenses;
- unpaid medical expenses;
- vocational rehabilitation;
- disputed benefits; or
- some combination of these items.
Some settlements close virtually every aspect of the workers’ compensation claim. Others resolve only particular benefits while leaving certain rights open.
That distinction can be enormously important.
A worker offered $80,000, for example, cannot sensibly evaluate the offer from the number alone. If future medical care remains available separately, that $80,000 means something very different than if the worker must use the settlement to pay for every future surgery, medication, injection and specialist appointment arising from the injury.
The written settlement agreement matters at least as much as the headline amount.
Future Medical Care Can Be One of the Biggest Unknowns
Future medical expenses are particularly difficult to value when an injury may require years of care.
A worker with a permanent orthopedic injury might eventually need another operation. Someone with a spinal injury might require pain management, medication or periodic injections. A serious neurological injury could require much more extensive long-term care.
Once future medical benefits are closed by settlement, the worker may become responsible for costs previously paid by the workers’ compensation insurer, subject to the exact settlement terms and applicable law.
This is one reason settlement negotiations frequently become more serious after the medical condition stabilizes.
It is also why a seemingly large lump sum may not be as generous as it first appears.
Medicare Can Complicate Some Settlements
Federal Medicare rules can add another layer when a workers’ compensation settlement includes future medical expenses.
The Centers for Medicare & Medicaid Services explains that a Workers’ Compensation Medicare Set-Aside Arrangement, or WCMSA, may allocate part of a settlement to future medical services related to the work injury that would otherwise be covered by Medicare. CMS says parties resolving workers’ compensation cases involving future medical expenses have responsibilities to consider Medicare’s interests.
Not every workers’ compensation settlement requires CMS review of a Medicare set-aside. Whether Medicare issues must be addressed depends on the worker’s circumstances and the structure of the settlement.
For affected workers, however, Medicare considerations can materially change both settlement negotiations and how part of the settlement money must subsequently be managed.
A Settlement Offer Does Not Have to Be Accepted
Receiving an offer is not the same thing as being required to take it.
Workers’ compensation settlements are generally negotiated agreements. A worker may accept an offer, reject it or make a counteroffer.
The insurance company has its own reasons for settling. Closing a claim can convert uncertain future obligations into a known present cost. The worker may also have reasons for wanting finality, such as avoiding prolonged disputes and receiving control over a lump sum.
Those interests do not necessarily mean the first number proposed represents the true value of the claim.
Before accepting an offer, questions worth considering include:
- Has the medical condition stabilized?
- Is additional surgery possible?
- Are future medications or therapy likely?
- Will medical benefits remain open?
- Are permanent work restrictions expected?
- Can the worker return to the same occupation?
- What benefits are being surrendered?
- Are unpaid medical bills addressed?
- Could Medicare have an interest in the settlement?
- What happens if the condition deteriorates later?
Workers facing those questions may decide to obtain legal advice before signing a final agreement. For example, an injured employee considering a Florence, Kentucky claim may consult a specialist workers’ compensation lawyer to understand how that state’s rules affect a proposed settlement.
That review can be particularly important because, once a final settlement has been approved, reversing it may be difficult or impossible except in limited circumstances.
Settlements Often Require Formal Approval
Even after the worker and insurer agree on a number, the matter may not be finished.
Many state systems require settlement agreements to be submitted to the workers’ compensation authority or an administrative law judge for approval.
In North Carolina, agreements to pay compensation must be approved by the Industrial Commission.
In Kentucky, settlement agreements are reviewed for compliance and ultimately approved or disapproved by the appropriate administrative law judge.
These procedures provide an additional layer of oversight, although the precise requirements differ by jurisdiction.
Consequently, “we have agreed on a settlement” and “the settlement is final” may not occur on the same day.
A Denied Claim Can Still Eventually Settle
A denial does not necessarily mean settlement is permanently off the table.
An insurer might dispute whether:
- the injury happened at work;
- the worker was legally an employee;
- the medical condition was caused by the workplace incident;
- the employee gave proper notice;
- particular medical treatment is necessary; or
- continuing disability is related to the original injury.
When liability is disputed, the worker may have to pursue the state’s formal claim, mediation, hearing or appeal procedures.
Settlement can still become possible during that process.
In fact, disputed claims sometimes settle precisely because both sides face uncertainty. The worker risks receiving less than expected, or nothing, while the employer and insurer risk being ordered to pay benefits after a hearing.
Settlement allows both sides to replace some of that uncertainty with an agreed result.
What Happens if the Employer Has No Workers’ Compensation Insurance?
An uninsured employer creates a different problem.
Most states require many employers to carry workers’ compensation insurance, although coverage rules and exemptions differ.
When an employer that should have insurance does not, the worker may need to use a special state procedure rather than follow the normal insured claim process.
The important point is that lack of insurance should not automatically be interpreted as meaning there is no possible remedy.
The available options are highly state-specific, so an injured worker in this situation should promptly determine which state agency handles uninsured-employer claims and whether filing deadlines apply.
Third-Party Claims Can Exist Alongside Workers’ Compensation
A workplace accident is not always caused solely by the employer or the injured employee’s coworkers.
Imagine a delivery driver who is struck by another motorist while making deliveries. The driver may have a workers’ compensation claim because the collision occurred during employment, but there may also be a personal injury claim against the negligent driver.
Other examples could involve:
- defective machinery;
- unsafe equipment manufactured by another company;
- a negligent subcontractor;
- a dangerous property condition controlled by someone other than the employer; or
- another driver involved in a work-related road accident.
A third-party claim is legally separate from workers’ compensation and may allow recovery of damages that are not ordinarily available through the workers’ compensation system.
However, the two claims can interact.
Workers’ compensation insurers may have statutory reimbursement or subrogation rights against money recovered from a responsible third party. Exactly how those rights operate depends on state law.
This means settling the third-party case without first understanding the workers’ compensation consequences can produce an unpleasant surprise. Part of the recovery may need to satisfy a lien or reimbursement claim.
Why Some Claims Settle Quickly and Others Take Years
There is therefore no useful answer such as “workers’ compensation usually offers a settlement after six months.”
A relatively straightforward injury may stabilize quickly. The employee returns to work, future treatment is minimal and everyone agrees about the permanent impairment. Settlement may be comparatively simple.
Contrast that with a worker who suffers multiple fractures and a spinal injury, undergoes several operations, cannot return to the former occupation and has doctors discussing additional surgery.
It could take considerably longer before anyone can responsibly estimate future medical and disability costs.
Other factors that may slow settlement include:
- disagreement over the medical diagnosis;
- multiple injuries;
- surgery that has not yet occurred;
- disputes over impairment ratings;
- unresolved return-to-work issues;
- disagreement about average weekly wages;
- Medicare considerations;
- third-party litigation;
- unpaid medical bills;
- questions over insurance coverage; and
- formal appeals.
The absence of a settlement offer therefore does not necessarily indicate that something has gone wrong. Sometimes the claim simply has not reached a point where either side can confidently put a final number on it.
The Settlement Amount Is Only Half the Question
Workers naturally want to know what their claim is worth, but the better question is often what the proposed settlement is intended to replace.
A $100,000 settlement that leaves lifetime medical treatment open could be considerably different from a $100,000 settlement that closes all future medical and disability rights.
Likewise, receiving a lump sum today has advantages, but giving up long-term benefits transfers future financial risk from the insurer to the worker.
That is the central trade-off in many workers’ compensation settlements.
The insurer gains certainty about its future costs. The injured worker gains certainty and control over the settlement proceeds, but may also assume responsibility for expenses and risks that the workers’ compensation system previously carried.
The Bottom Line
Workers’ compensation does not automatically offer a settlement at a predetermined stage.
Settlement discussions often become more realistic once the worker’s medical condition has stabilized, doctors understand any permanent impairment, future treatment can be estimated and the worker’s ability to return to employment is clearer.
But every claim develops differently, and every state has its own workers’ compensation system.
A settlement can offer valuable closure, particularly when the amount fairly reflects the worker’s medical needs, disability and future earning situation. At the same time, accepting a settlement can involve giving up important rights that may be difficult to recover later.
That makes the details critical.
Before focusing solely on the size of a settlement check, an injured worker should understand exactly what benefits the agreement resolves, what remains available afterward and who will be responsible for future medical treatment.
In workers’ compensation, the most important question is rarely just “How much are they offering?”
It is “What am I giving up in return?”